Mike Vinokur thinks a market washout could be just two to four weeks away—and that may be the time to buy. The Portfolio Manager & Senior Wealth Advisor at Propellus Wealth Partners with iA Private Wealth has raised cash to nearly 30% in his growth portfolio as the S&P 500’s double-digit gain masks a much uglier market underneath. High-quality stocks are down 20%, 30% and even 40%, and Mike joins Amber Kanwar to explain why he thinks more pain could be coming before a potentially compelling buying opportunity emerges.
Looking to invest in high-quality companies without high fees? The HAMILTON CHAMPIONS™ suite of ETFs offers exposure to diversified portfolios of equity champions across tech, financials, utilities, and dividend strategies, all with a low 0.19% management fee, designed to help you stay invested with confidence for the long term. For more information on the HAMILTON CHAMPIONS™ suite, visit: www.hamiltonetfs.com/hamilton-
FROM AMBER’S DESK
To the people who voted for us in the Signal Awards – thank you isn’t enough. I appreciate you took the time and went through the agony of creating yet another username and password. You moved the needle and we are now 2nd and 3rd place in our respective categories. Unfortunately, my Indian upbringing means these are worse defeats than never having placed at all. So please, for my ancestors….vote for us HERE and HERE!
Here are five things to know today
1.
Stocks get a lift as oil and bond yields retreat
Let’s start with the good news: the S&P 500 is near a record high and the NASDAQ hit another one yesterday. The TSX is struggling after a bad month in September but is only 4% away from a record high. It might feel hard to be excited about this because under the hood things are still pretty soft. Tech is carrying the day and not much else. The equal-weight S&P 500 is down 3% over the past month vs the market weight index which is flat. So what do we do now? We could see a further wash out argues Mike Vinokur on today’s episode, but that’s when investors should sharpen their pencils. Vinokur, who is sitting 30% in cash, says he will be ready to go shopping with a long list of names on his watch list that have been pummeled in secret because the index is masking underlying weakness.
Now to the situation in France. We are seeing a reprieve from selling pressure in the bond and equity market, but things are starting to come to a head. A combination of high energy prices, rising interest rates to combat inflation and weak fiscal discipline have conspired against the French economy and created a high degree of political instability. French bond yields have blown out by 100 basis points in the past 3 months and the equity market is down 3% so far this year. The country needs austerity, a four letter word anywhere but particularly hard to sell in France. “The silver lining is that restless bond markets are forcing Prime Minister Sebastien Lecornu’s minority government to act,” wrote Ed Yardeni of Yardeni Research, “Hovering in the background is an even more unsettling possibility: “Frexit” Le Pen’s nationalist and euroskeptic rhetoric continues to unnerve investors, particularly given her support for costly measures and opposition to some of Macron’s most important reforms.”

2.
Emera to buy Canadian Utilities while ATCO to get spun out
The combination of Emera and Canadian Utilities will create a top 20 North American utility with combined $72 billion in enterprise value servicing 6 million customers in what could be the largest deal ever between two Canadian companies. The deal is “creating a Canadian utility and energy infrastructure powerhouse with the scale to help power Canada’s growth ambitions…” stated the press release. Much of the language of the deal reads like a continuation of the Canada Investment Summit.
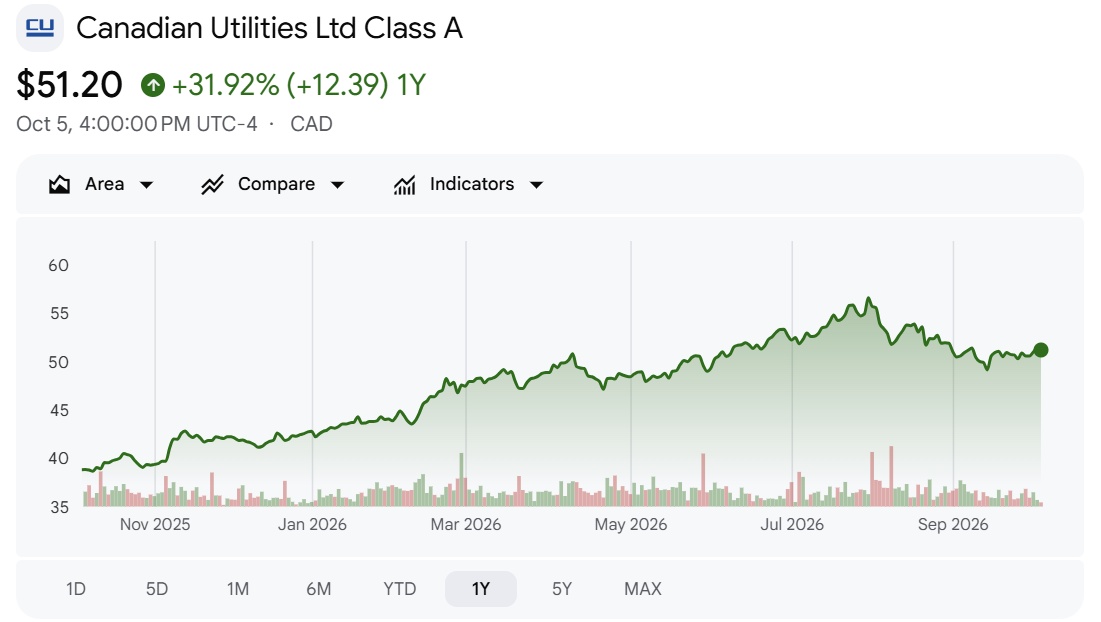
Here are the nuts and bolts of the deal: Emera shareholders will get 60% of the new company, while Canadian Utilities & ATCO shareholders will own about 40%. As part of the deal, ATCO will be spun out into a “high growth industrial services company focused on housing, defence, and investments including ports and retail energy.” Again, very Build Canada coded. Currently, the Southern family led by Nancy Southern (whose father founded ATCO) control both Canadian Utilities and ATCO. Shareholders of ATCO will receive shares in both the combined company and new ATCO. The dual class voting structure, controlled by the Southerns, will continue at new ATCO. Shareholders of Canadian Utilities (Class A) will receive 0.75 Emera shares which works out to $51.22 per share – basically exactly where Canadian Utilities was trading yesterday.
3.
Toronto home prices fall again
Prices were down for a second month in a row and are down nearly 5% from last year. Home sales also dropped 5.2% from last year. As a result, potential sellers are sitting on the sidelines with new listings down nearly 4% from the previous month. Real estate is a confidence game, if you are going to take out a mortgage at higher rates you need to feel secure in your job and your ability to pay other bills. The decline in both prices and sales reflects shaky confidence. And yet even with further evidence of a weaker housing market, Canadian bank stocks have been remarkably resilient up nearly 30% so far this year. Perhaps vindication for a sector targeted by US short sellers predicated on a housing bubble thesis. Or potentially making them more vulnerable again? I will bring this up in my interview with famed “Big Short” investor Steve Eisman later this week. He famously was short the Canadian banks back in 2019.
4.
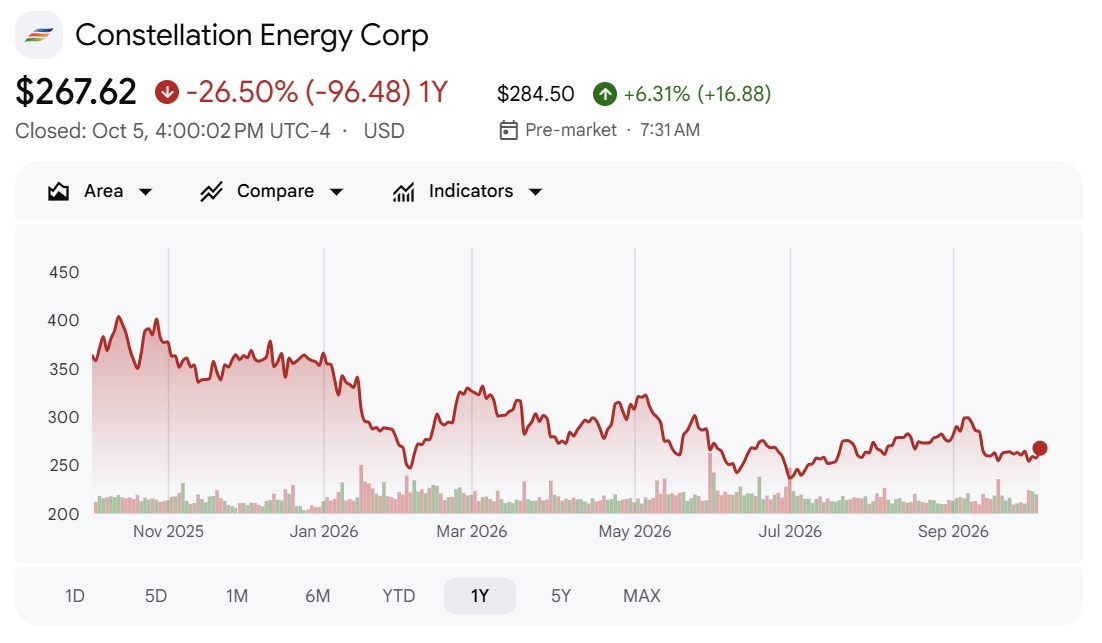
Constellation Energy +6% on Google power deal
The clean energy power generator inked a 20-year agreement that would see it adding 890 megawatts of nuclear power to a key north eastern power grid. Google will provide the financing to expand six operating nuclear plants across Pennsylvania, Illinois and New Jersey (PJM grid). No financial terms were disclosed but Constellation said the deal will enable $4.3 billion on building out the capacity to meet the new demand.
5.
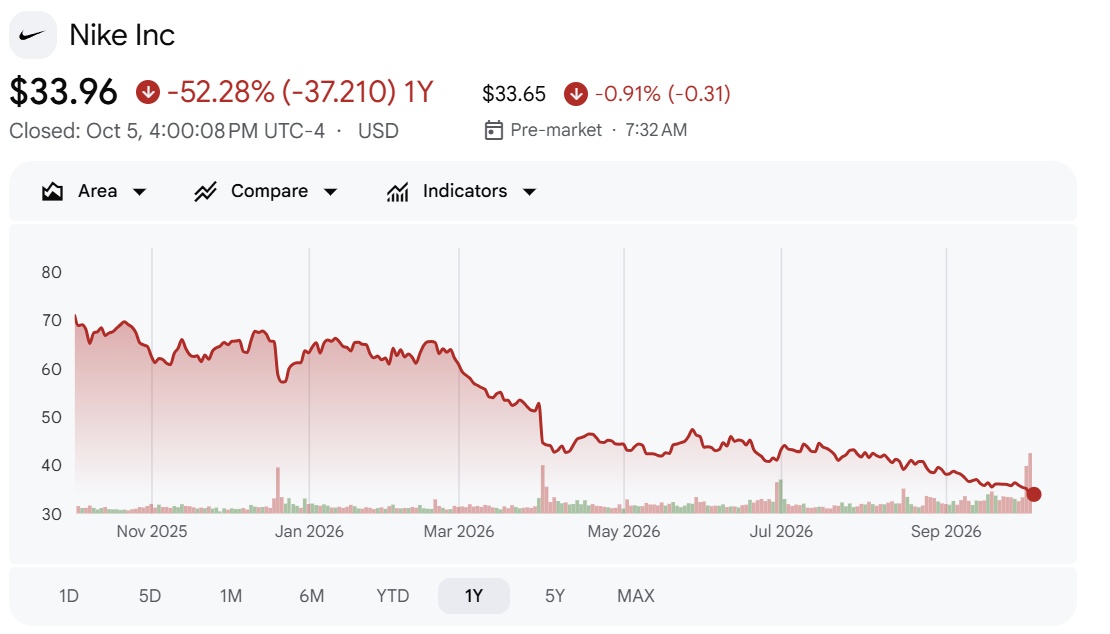
Nike cut to sell at Berenberg
Stop me if you’ve heard this before: Nike cut to sell while trading at a 13-year low. This time it is a downgrade from an analyst at Berenberg. “Nike appears to have accepted a smaller place in sportswear,” wrote Berneberg’s Nick Anderson. Ouch. I should have cut this one loose but still have it in the portfolio. Anderson argues that in addition to reduced market share a turnaround in China is “not a sure thing.” While the stock has been on the mat, Anderson warns of potentially 19% downside from here.
Don’t miss the next episode!