Mike Vinokur thinks a market washout could be just two to four weeks away—and that may be the time to buy. The Portfolio Manager & Senior Wealth Advisor at Propellus Wealth Partners with iA Private Wealth has raised cash to nearly 30% in his growth portfolio as the S&P 500’s double-digit gain masks a much uglier market underneath. High-quality stocks are down 20%, 30% and even 40%, and Mike joins Amber Kanwar to explain why he thinks more pain could be coming before a potentially compelling buying opportunity emerges.
Looking to invest in high-quality companies without high fees? The HAMILTON CHAMPIONS™ suite of ETFs offers exposure to diversified portfolios of equity champions across tech, financials, utilities, and dividend strategies, all with a low 0.19% management fee, designed to help you stay invested with confidence for the long term. For more information on the HAMILTON CHAMPIONS™ suite, visit: www.hamiltonetfs.com/hamilton-
FROM AMBER’S DESK
It is producer Jillian’s birthday today! I offered her a lavish lunch, jewels and a day at the spa to celebrate. But she turned it all down and said all she wants for her big day is for us to win a Signal Award. Make her dreams come true….vote for us HERE and HERE!
Here are five things to know today
1.
Market jitters take hold once again
The S&P 500 hit a record high for the first time since August along with the NASDAQ but this morning there is renewed selling pressure as yields are once again rising. The US 10-year yield hit 5.3% – surpassing the highs of 2007 to hit the highest level since 2002. The big question investors need to ask is whether strong equity markets are a sign of complacency or resilience. Citi says it is the latter this morning. “Citi’s House View sees geopolitical risks subsiding before year-end, with global growth coming in just below its trend rate,” wrote Citi’s head of global and European equities, Beata Manthey, “This sets up for decelerating, but still-solid global EPS growth in (2027) (consensus sees +16%), which can support further gains from here.”
The US government will be selling 10-year bonds today at auction – a typically mundane normal-course event – but will be closely watched for demand and the yields at which it is sold. Investors will be particularly interested in foreign demand. Are high yields tempting enough to increase foreign appetite for treasuries? The minutes from the last Federal Reserve meeting in which they increased interest rates for the first time since 2023 will be out later today as well. Investors will look for clues about rate path with the market pricing in just a 21% chance of another rate hike at the end of the month.
How’s the TSX doing? Since the peak at the end of August the index has struggled and in many ways reflective of the broader market trend: tech is working and not much else. Gold has been under pressure dragging down materials while the rally in crude hasn’t helped our energy stocks much. Since the TSX made a record high on August 25th, every sector is in the red except for tech which isn’t enough to hold up the index.

2.
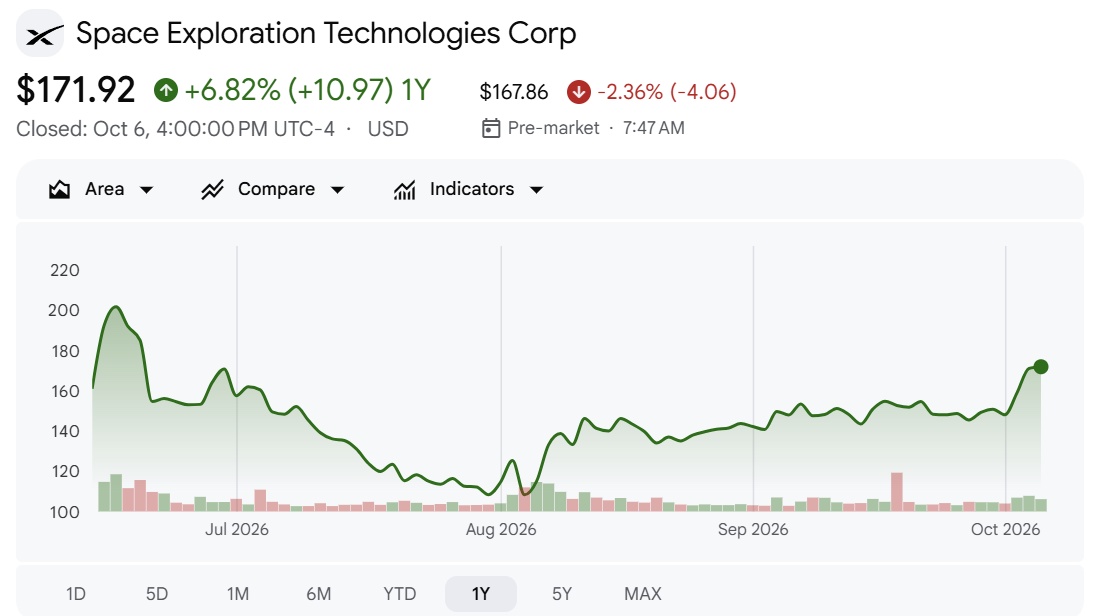
SpaceX drops on reports it is seeking $40 billion in financing
Fresh funds are needed to buy Nvidia chips and would be financed entirely through debt. The report scratches at an itch in the markets about how much these hyperscalers need to raise in debt to finance their AI ambitions. These kinds of issuances have been partly blamed for the sell-off in government bonds because they are crowding out demand. This would be the biggest debt-fueled financing for the AI buildout to date. “Locking in Nvidia chip supply with debt rather than equity is the capital-efficient answer,” wrote Dan Ives of Yorkville Ives (welcome back Dan!), “It avoids returning to the equity market four months after the June IPO, it funds capacity that is being contracted ahead of delivery…The debate is whether a company this early in its public life should carry that much leverage. We think the contracted backlog in AI and the cash generation of Starlink give SpaceX the capacity to service it, and we would rather see this compute financed and deployed than deferred.”
Let’s spend a minute on Apollo Management which is leading the financing. “(This) could be a moderate catalyst for the sector given depressed sentiment,” wrote TD Cowen’s Bill Katz. He says leading a deal of this size requires scale, something only a handful of companies could do and Apollo is one of them. While this specific deal may not be meaningful to the bottom line, it speaks to the opportunity for private credit to get in on financing the AI infrastructure buildout at a time when the market is punishing them for their software bets.
3.
Activist circling Under Armour
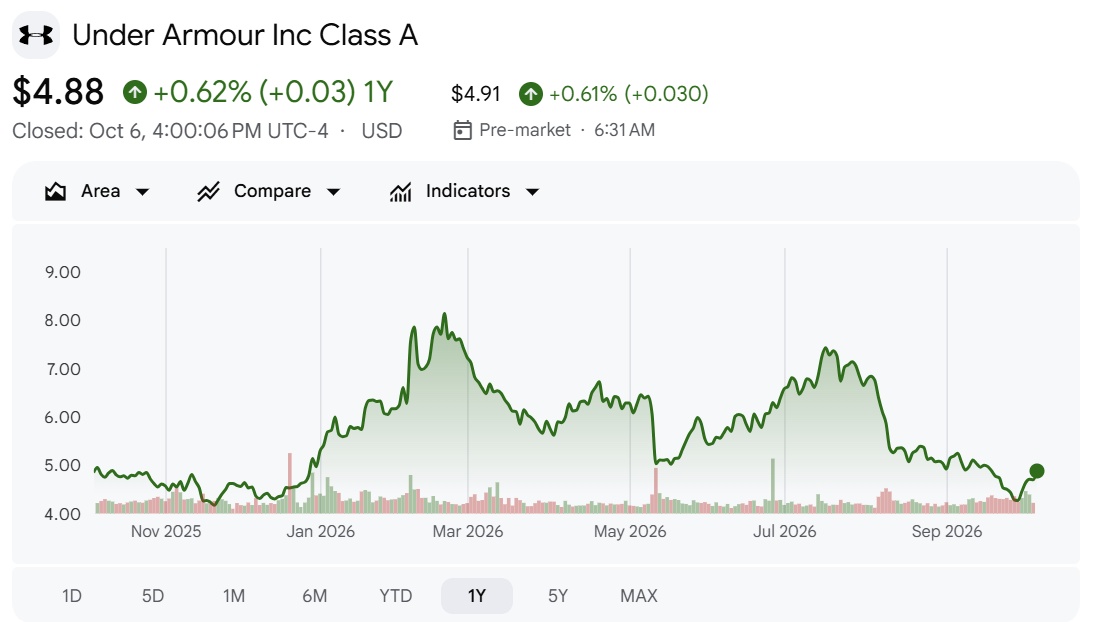
UK billionaire, Mike Ashley, has taken a stake in the embattled sports brand. Ashley, who was the founder of Sports Direct, now manages assets through Frasers Group Plc and is known to take stakes in floundering retailers. Sometimes he does nothing while a shareholder, sometimes he agitates for change or a sale. Unclear what his plans are here at the moment, but it comes at a time when the whole category has been challenged. The stock has lagged, down 2% in 2026. But at 46x forward earnings, it is hardly a steal. Especially considering sales and profit have been falling for two years in a row. Back in August Under Armour cut its outlook citing a “challenging consumer demand environment.”
Of course, Under Armour isn’t the only dog at this show. Nike has done worse, down 44% so far this year. Larry McDonald is making the case of buying Nike stock at these levels in his Bear Traps report this morning. “Think of a hurricane. Nike’s capitulation is a CAT-5,” he wrote saying that tax-loss season could be the final flush in shares. Category 5, says McDonald, is when a stock is trading at an extreme disconnect from its 200-month moving average. “The precedent is ExxonMobil in November 2020, an epic Hall of Fame Category 5 bottom. The same for Alibaba in 2022, and Intel in August 2024. Last year, Target had a similar Q4 washout and was 60% higher by the second quarter. When the factors line up this extremely, the probability of a meaningful return over the next six months is very high.” With a nearly 5% dividend yield, he says you are getting paid to wait for a recovery. Although if it drops another 40% that will likely not matter. I’m not sure if McDonald will be right, but it’s definitely a contrarian take amidst a rash of downgrades. I’m hanging on with a very small position.
|
“Looking out toward the 2028 LA Olympics, you’re getting paid close to 5% to wait, and the setup points to a potentially huge move — we see well over 100% return by the Games. If Nike gets back to its old highs, it needs close to a 370% return” — larry mcdonald, bear traps report |
4.
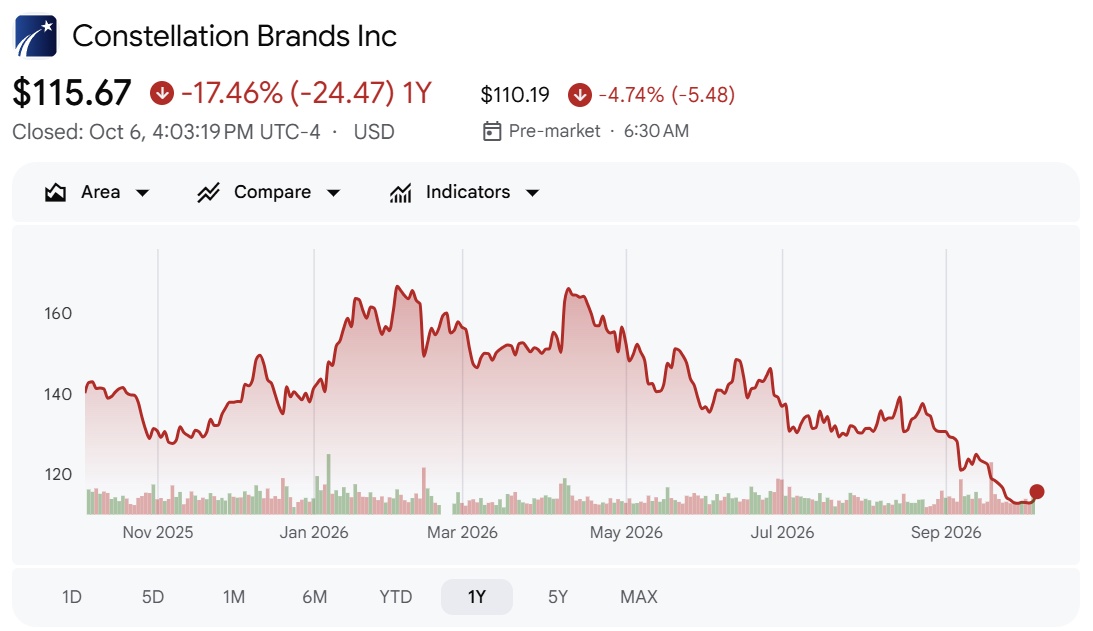
Constellation Brands -5% on disappointing outlook
The owner of alcohol brands like Modelo and Corona beat profit expectations in the current quarter but maintained its full year outlook implying weaker growth ahead. Blemishes in the quarter include a continued slide in beer sales at distributors while the outlook for beer margins was weaker. Owning the stock has been a buzzkill – shares are down 17% over the past year as it struggles under the weight of lower demand and higher input costs.
Constellation also announced it purchased SpikedAde for $75 million with a $278 million earnout over 5 years. The deal will allow it to compete in the “emerging sports drink-inspired ‘Ade’ segment,” said the company in a release. Just what my Gatorade has been missing – VODKA!
5.
TD upgrades Canadian Utilities & ATCO amidst deal
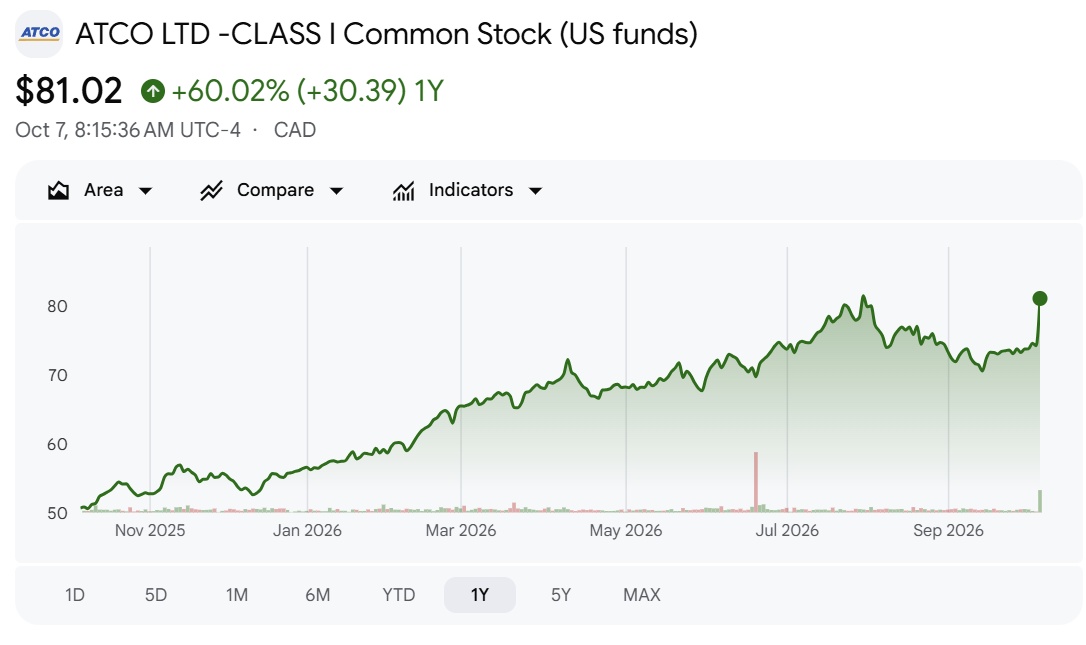
The Emera deal is putting ATCO back in the spotlight. TD Cowen’s John Mould upgraded ATCO to buy from hold and raised the target to $98/share from $76/share. The thesis is that spinning ATCO’s non-utility businesses out as “New ATCO” will finally let investors see, and pay for, what’s inside, especially the Structures business that builds modular and workforce housing. While the stock rallied nearly 10% yesterday following news of the deal, Mould believes there is still is about $10/share of upside to New ATCO that isn’t being reflected in the move. ATCO always traded at a discount because of the way it was structured and now that it will be spun out as a pure play, most analysts think that discount will narrow meaningfully.
He’s also upgrading Canadian Utilities on the back of Emera buying the company noting shareholders will be getting a 20% higher dividend once the deal goes through
Don’t miss the next episode!