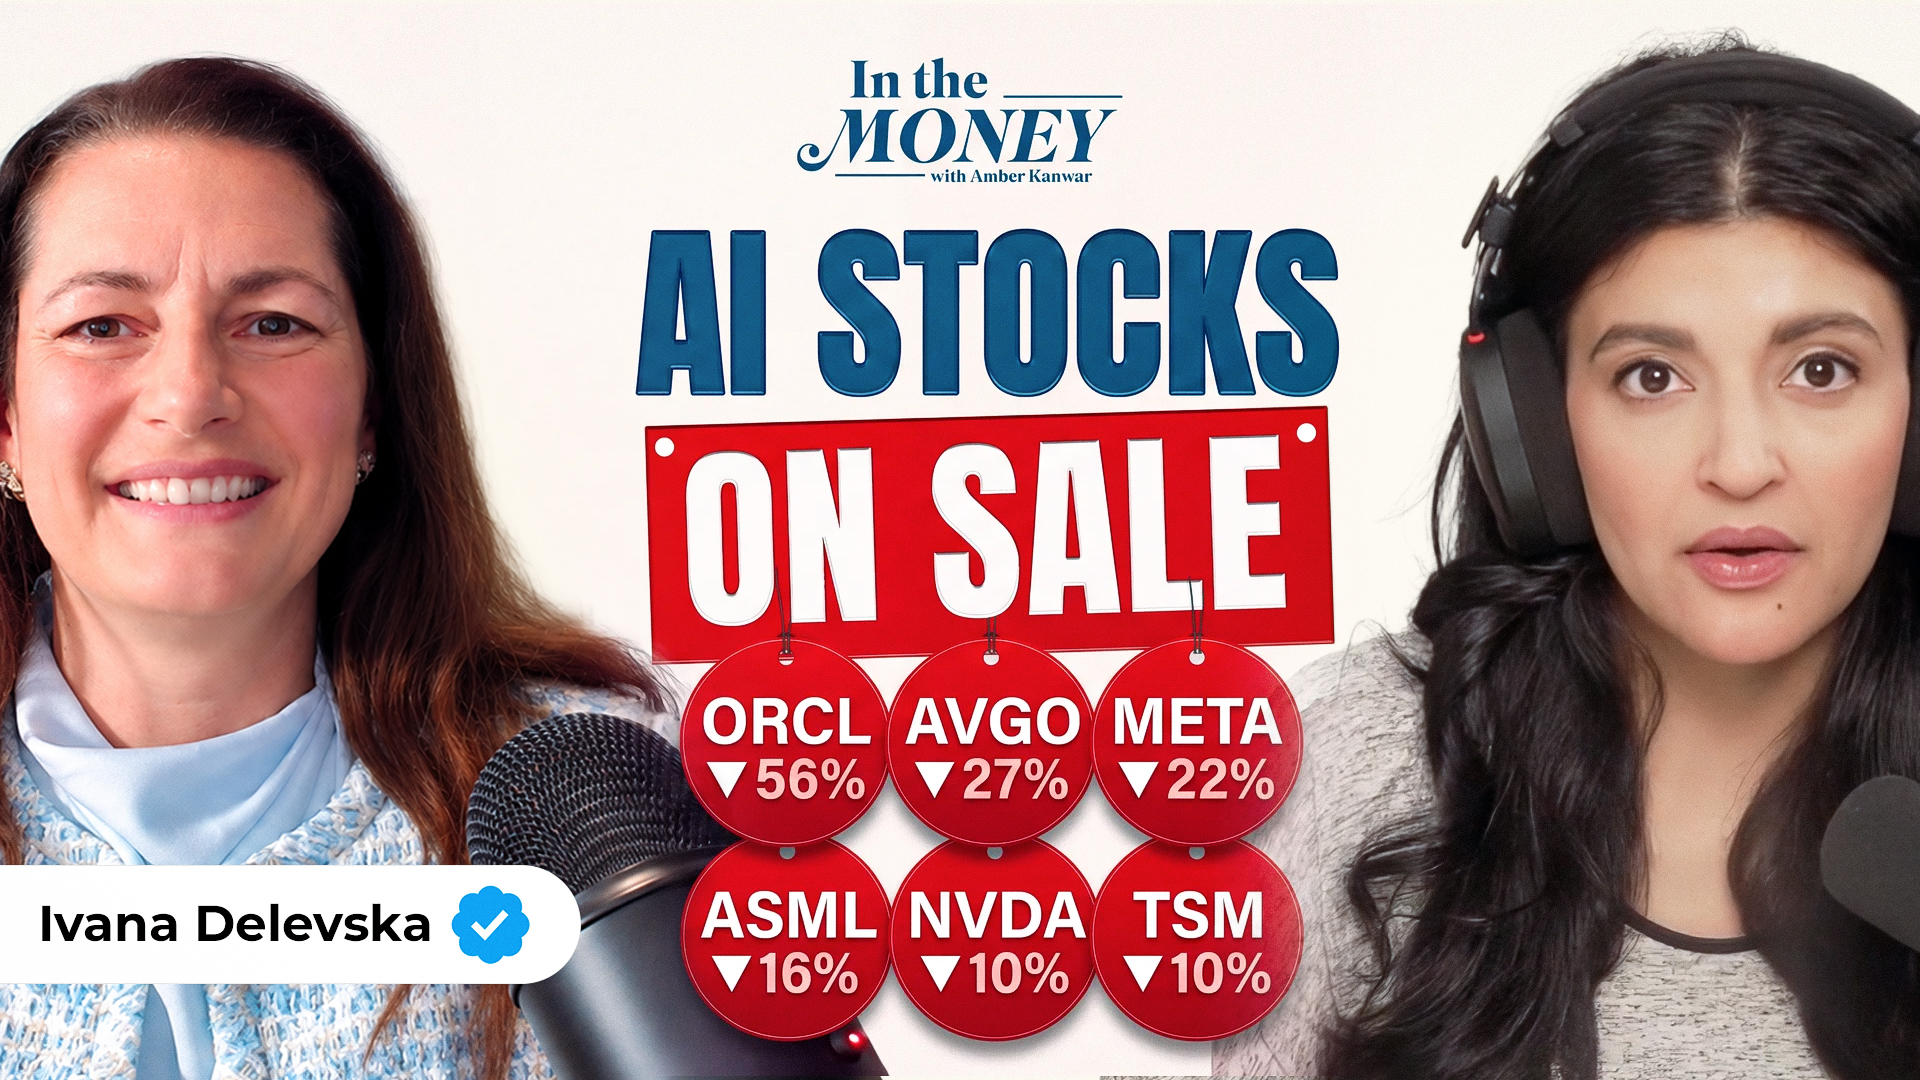
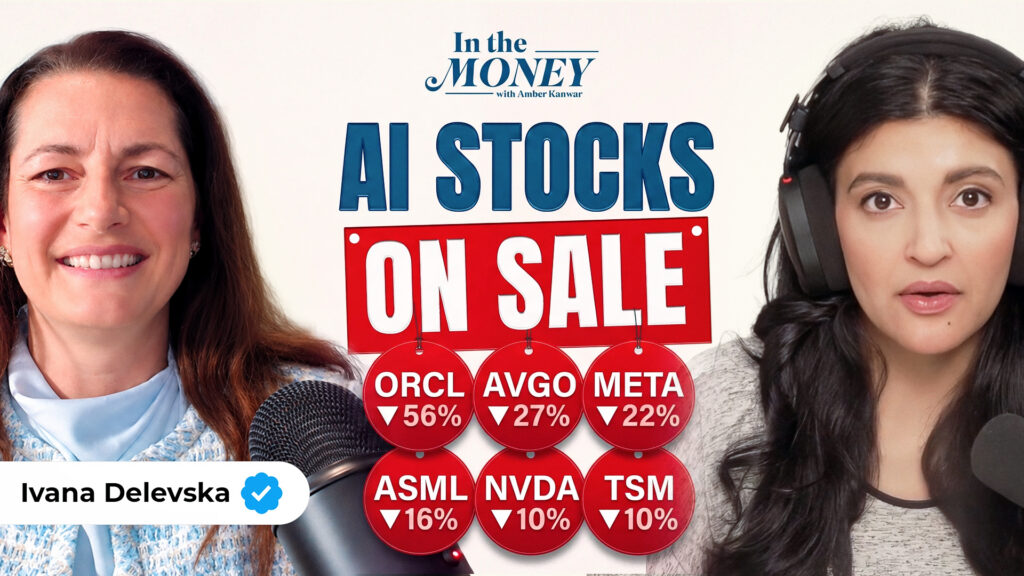
Tech stocks have been crushed, but Ivana Delevska believes the worst of the AI sell-off may be behind us. With some AI stocks down 30%, 40% or even 50% from their highs, is this the buying opportunity investors have been waiting for? And could the highly anticipated Anthropic IPO reignite the AI trade? On this episode of In the Money with Amber Kanwar, Ivana Delevska, Founder and Chief Investment Officer of Spear Invest, explains why rising interest rates and forced selling have hammered AI stocks, even as the underlying fundamentals remain strong.
Looking to invest in high-quality companies without high fees? The HAMILTON CHAMPIONS™ suite of ETFs offers exposure to diversified portfolios of equity champions across tech, financials, utilities, and dividend strategies, all with a low 0.19% management fee, designed to help you stay invested with confidence for the long term. For more information on the HAMILTON CHAMPIONS™ suite, visit: www.hamiltonetfs.com/hamilton-
FROM AMBER’S DESK
Last night was hosting an event with other content creators (which apparently I am). I love this group because we don’t have to pretend about what really matters in life. It isn’t money, not even family and friends. It’s views. A group that knows we only feel as good as our last viral video.
Here are five things to know today
1.
Stocks under pressure as Google earnings disappoint
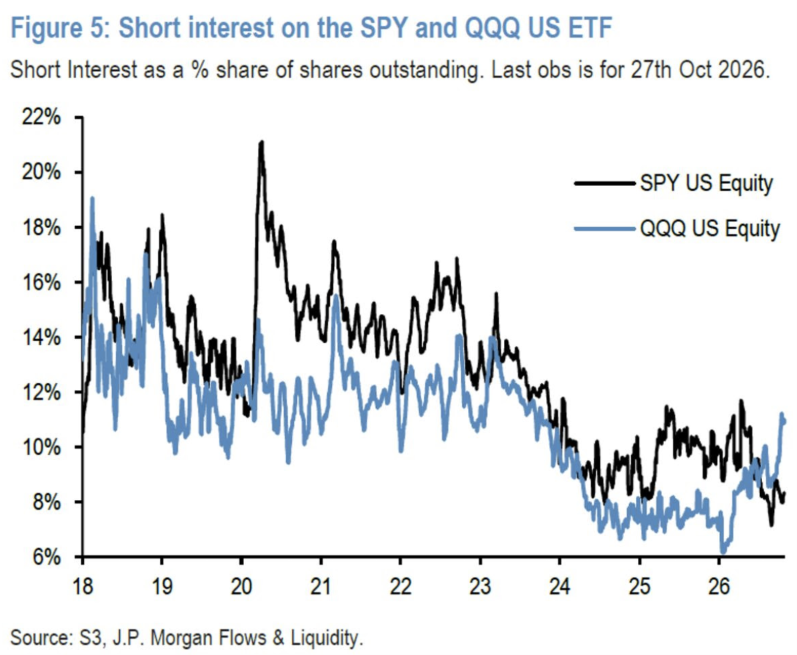
Let’s start with the good news: the S&P 500 is 1% away from a record high and the TSX is less than 2% away. Yesterday the Bank of Canada increased interest rates and signaled more could come while the Federal Reserve kept rates on hold. The fireworks were after the closing bell when Alphabet and Microsoft reported (more on that below). Google is weaker after hours and futures are down led by tech stocks. But that is not the only pain point. ServiceNow is down 19% after earnings missed and backlog growth slowed while Micron and SK Hynix are under pressure because of Samsung results. Investors are generally skittish about tech – a trade that has paid off over the last couple of months. But with short positions on the QQQ at the highest level since 2023 – we could see support from short covering if things stabilize (see chart).
We just got the Federal Reserve’s preferred gauge of inflation which showed inflation picked up to 3.6% year over year – the highest since May. However, this was in line with expectations and didn’t move the market too much. At the same time we got a read of US Q3 GDP which was better than expected showing 3.4% expansion – better than the 3.2% expected. Consumer spending was also better and business investment grew nearly 13% thanks to AI spending. Net-net growth trumps inflation concerns.

2.
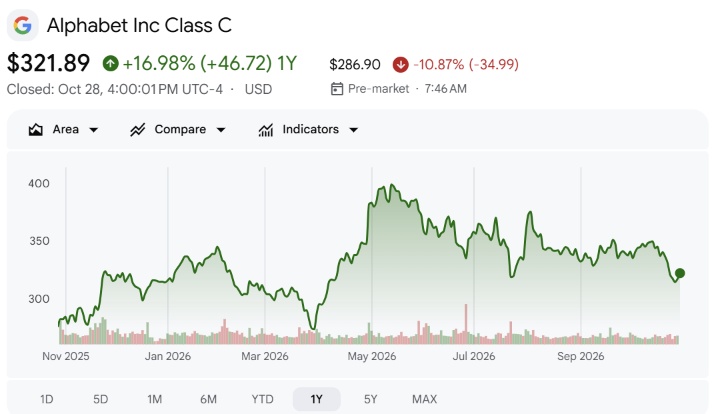
Google drops 11% after earnings miss
Let’s start with the bad news: earnings and sales missed expectations, free cash flow was negative for a second quarter in a row, and search revenue only grew 12%. On the bright side, cloud revenue doubled from last year but it wasn’t enough to offset everything else. So what happens to the stock now? “We believe shares will likely now be range-bound until a) GOOGL can show greater traction in Search AI monetization, b) the market better understands TPU costs, and c) we gain greater visibility into the magnitude and timing of trough FCF levels,” wrote Evercore’s Mark Mahaney.
The irony about the miss on search revenue is that search query growth was the highest in 5 years. People are increasingly using AI mode on Google but the problem is that the monetization rates are lower. The key will be whether Google can increase their monetization efforts. The other issue investors are grappling with is their new division that sells Tensor Processing Unit – a custom Google chip that was developed to run AI systems. While it was a clear contributor to growth, the company didn’t break out standalone revenue and margins. So that is creating question marks around the cost of getting into this business. I own Google.
|
“We believe this is a quarters – not years –transition, so we’ll maintain our Outperform.” — mark mahaney, evercore |
3.
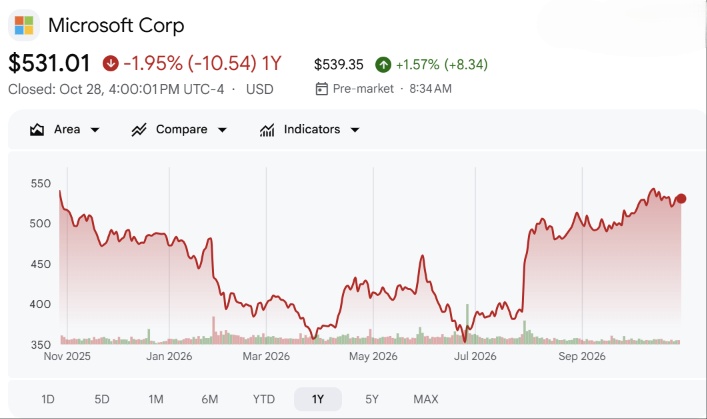
Microsoft flat despite stellar results
After an impressive 40% rally in the last three months, Microsoft investors appear to be out of gas despite better than expected profit and sales, 48% (!!) cloud growth, and lower cash burn than expected. Analysts were expecting its cloud business to grow 45%, so an increase of 48% cleared a very high bar. Not only that, Microsoft says next quarter could be even higher with growth between 49-50%. “Microsoft continued to show strong profitability and disciplined spending even as capital expenditures move higher in the 2H on the back of stronger demand,” wrote Citi’s Tyler Radke. I own Microsoft.
Although Microsoft results were strong, some of their comments around capacity constraints are hurting the neoclouds this morning. Neoclouds buy Nvidia chips and rent them out. Last night Microsoft said there were delays of third party cloud compute capacity. Shares of CoreWeave, IREN and Nebius are all under pressure this morning on the back of those comments because if it was one of them that failed to deliver then that could suggest an earnings miss. Microsoft didn’t name the third party provider, so investors are out here guessing for themselves. “While these sorts of developments create headline risk for the industry, our sense is that the neocloud in question (as it relates to MSFT’s lower than expected CQ3 capex) is not CoreWeave,” wrote Evercore’s Amit Daryanani, “We would also point to CRWV’s track record of delivering performant infrastructure at scale…” I own a small position in CoreWeave.
|
Neoclouds hit on microsoft comments CoreWeave: -6% Nebius: -7% IREN: -5% |
4.
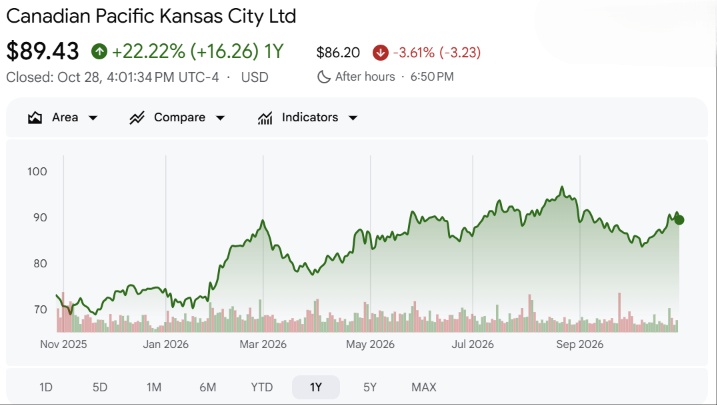
CP Rail -3% pre-market on earnings miss
Earnings were hit by higher fuel prices and stock-based compensation, offsetting strength in pricing and strong volumes. Total revenue increased 15% – the fastest since early 2023 – but the stock is up 22% over the past year so that may have been priced in. “We continue to recommend shares of Canadian Pacific Kansas City (CPKC) based upon the firm’s: 1) best-in-class network/operating momentum; 2) deep pipeline of embedded growth opportunities; 3) renewed commitment to shareholder-friendly policies (buybacks, dividend growth); and 4) attractive valuation relative to its superior long-term growth prospects,” wrote Steve Hansen of Raymond James.
CP Rail on NYSE
5.
Gold earnings disappoint: Eldorado, Kinross and Agnico Eagle all lower
Eldorado Gold is down 13% in pre-market after warning that production will be lower than expected. The gold miner cut its production forecast by 18% while also increasing its cost outlook by 16%. The tempered outlook reflects lower production out of its Turkish mine and northern Greek mine. While one of its biggest growth assets, Skouries, will ramp up slower than expected. All this combined pushes out the free cash flow inflection to later next year.
Kinross is sliding despite better than expected profit. Agnico Eagle is also under pressure on an inline quarter with slightly higher costs. Both stocks are under pressure as gold prices over all are weak against the backdrop of a rising US dollar.
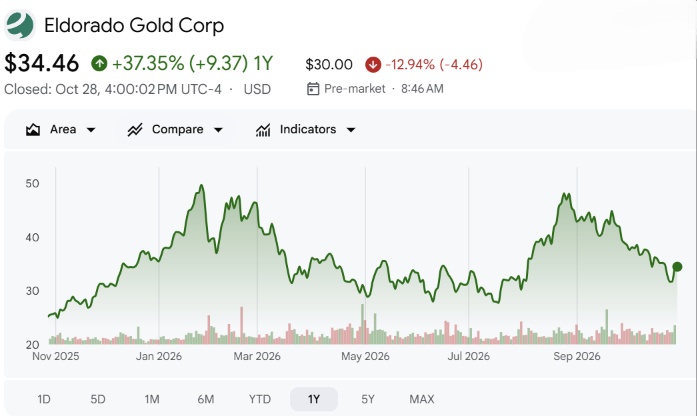
Eldorado on NYSE
Don’t miss the next episode! Time to get your questions in! Click here to submit a question!