In a world of higher rates, stubborn inflation and expensive U.S. stocks, Canada just might be your safest bet. Ryan Bushell, CEO & Portfolio Manager at Newhaven Asset Management, invests in Canadian dividend-paying companies—and his portfolio is up 18% so far this year. He joins Amber to explain why he thinks Canada is well positioned in this environment, why infrastructure and energy remain at the heart of his portfolio, and why he sees little reason to chase the U.S. market at current valuations.
Pro Picks is brought to you by ATB Financial. With over $100 billion in assets, ATB Financial is powering possibilities for more than 843,000 financial services clients. ATB Cormark Capital Markets is a leading North American investment firm providing holistic corporate and capital markets advice and full-service financial solutions. Visit www.ATB.com/inthemoney for more information.
Scorecard: Ryan’s past picks (October 23, 2025)
Pembina Pipeline (PPL): +31% · Still a hold.
The largest gas processor in Western Canada, and the opportunity set is only getting bigger with a possible LNG Canada Phase 2 decision and Trans Mountain optionality. He’d buy it again today.
Brookfield Infrastructure (BIP.UN): +10% · The favourite.
His preferred Brookfield name, dinged by rates and reorg noise despite largely inflation-protected cash flows. A ~5% yield and an underappreciated Western Canadian angle keep him buying the dip.
ARC Resources (ARX): +35% · The bittersweet takeout.
Taken out by Shell — but Newhaven isn’t celebrating losing a compounder they wanted to own for decades. Weakness at the Attachie project drove the sale they’d have preferred to ride out.
Top 3 Ideas: Betting on Canadian Energy Exports
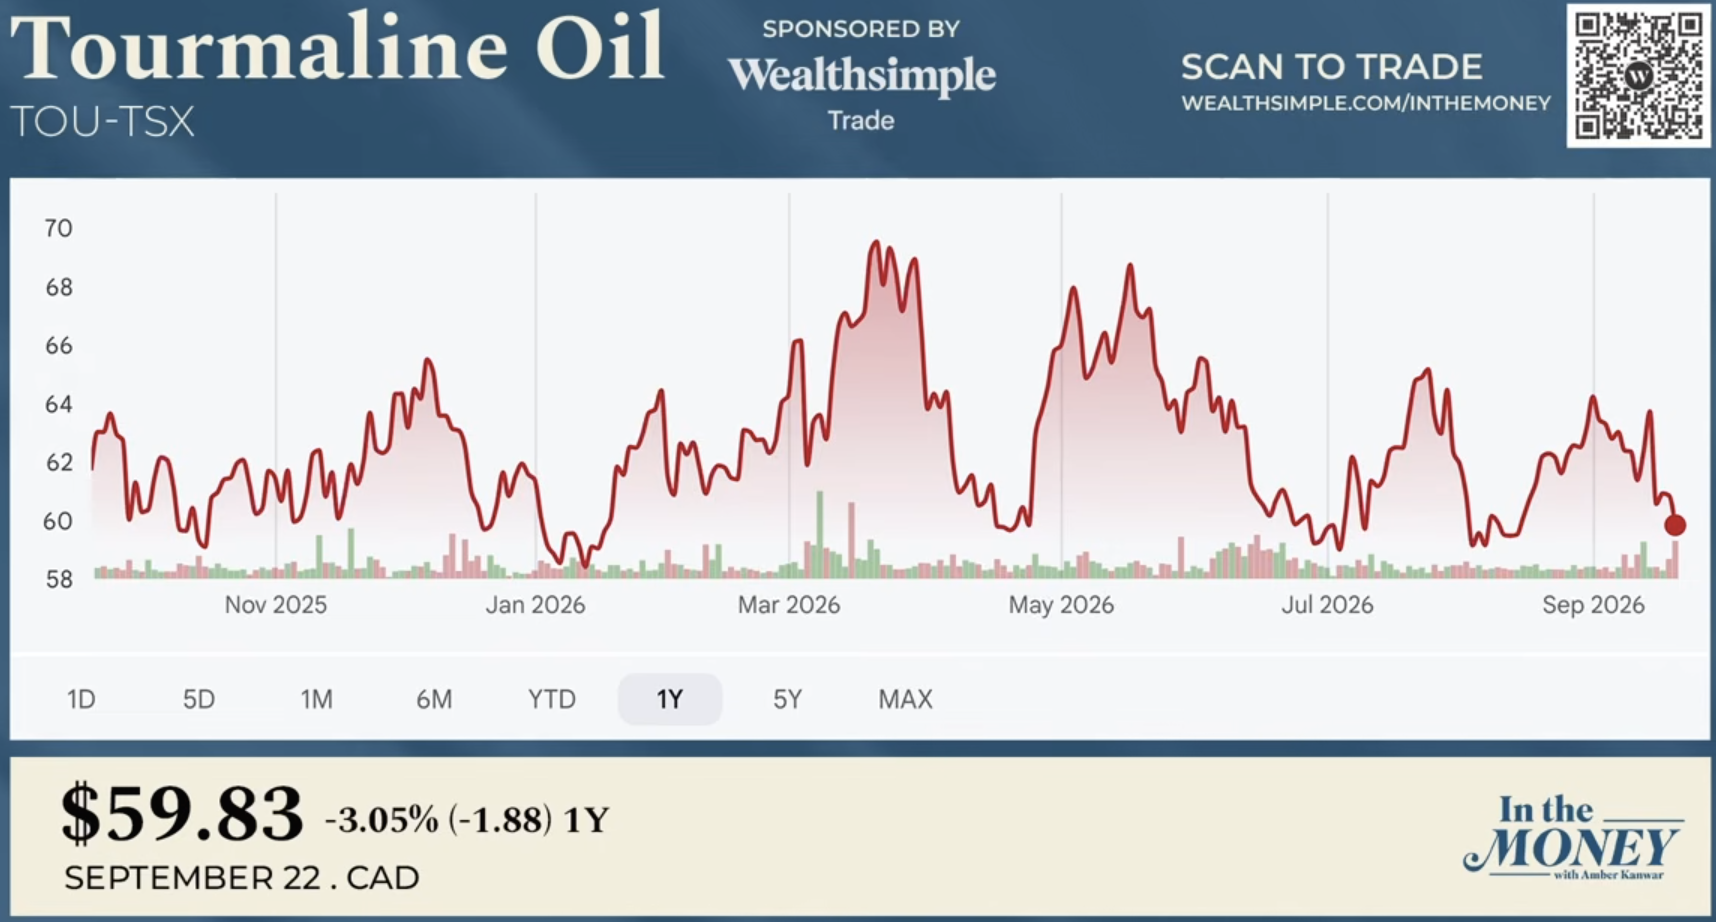
1. Tourmaline Oil (TOU) — the ARC replacement
Bought the day Shell took ARC out. Same Western Canadian gas theme, cleaner assets.
- A same-day swap. Newhaven bought TOU the day ARC disappeared, to keep exposure to the Western Canadian natural gas and LNG-export story.
- Built for the export era. Its marketing arm is already diversified across different LNG projects and benchmark prices.
- Cleaner than ARC — with one trade-off. No Attachie overhang, but less condensate exposure, which matters as oil expansion projects need more of it.
- The floor-price call. Coming off such a low base, even a 50-cent-to-$1 lift in the gas floor price makes you want to own it. Special dividends may slow in a spending cycle — but that’s a lever he’d rather have.
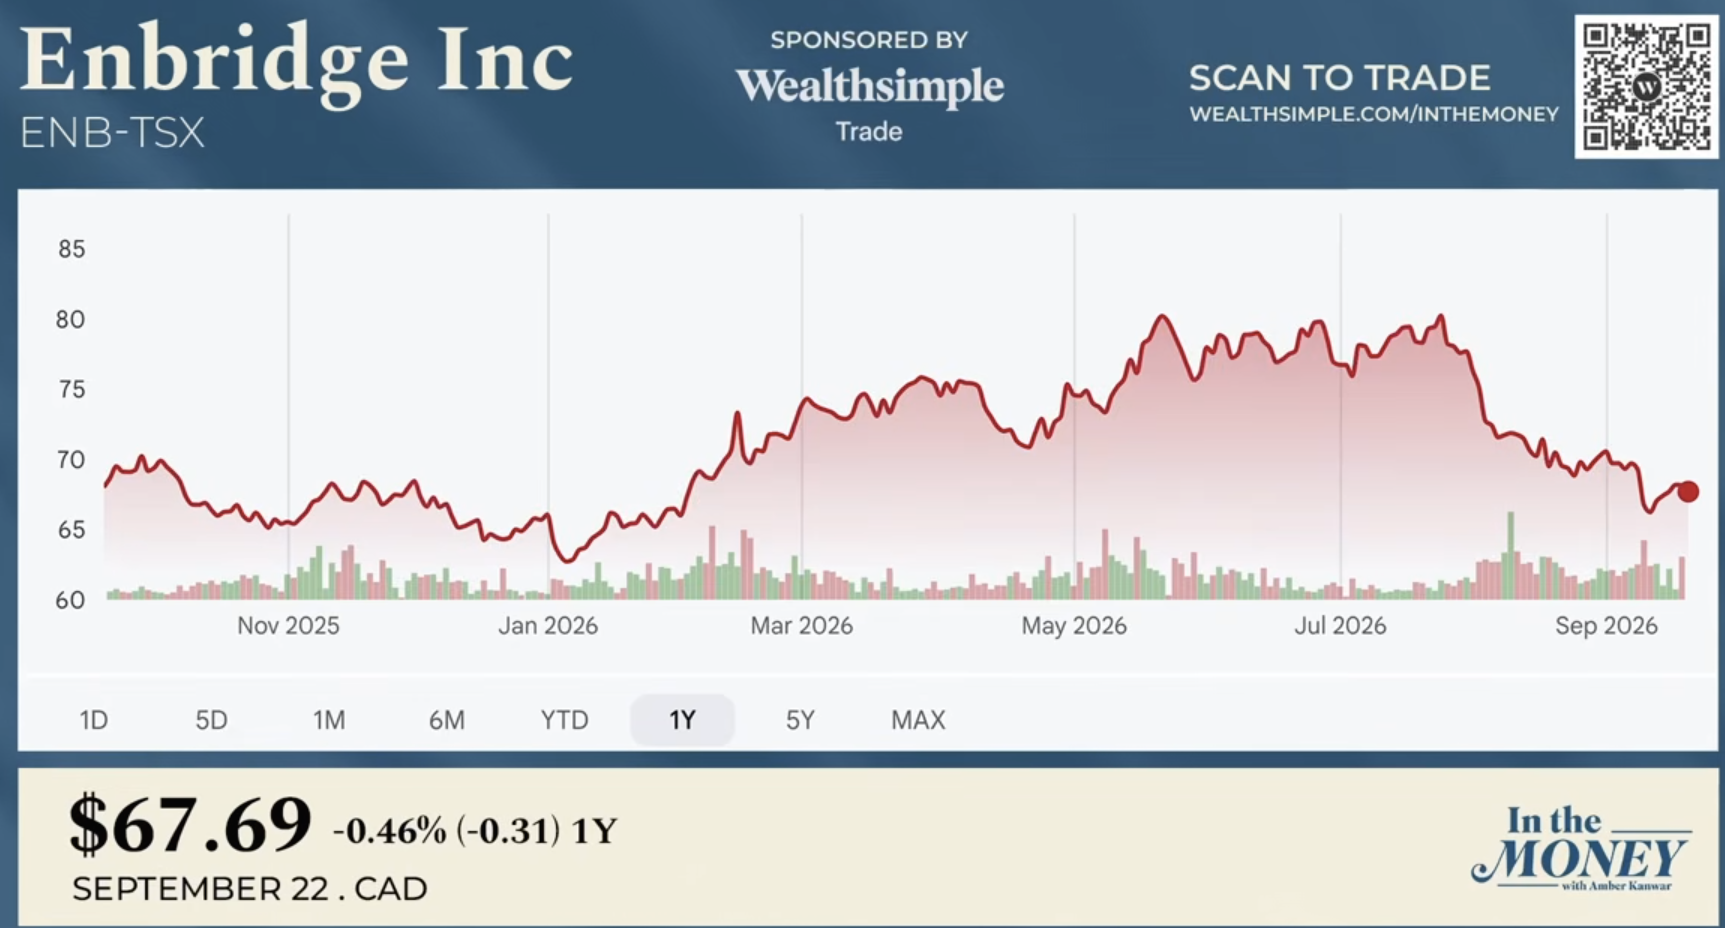
2. Enbridge (ENB) — the 6% anchor
Sold off on rates, now yielding roughly 6%.
- A defensive anchor. Ratable, high-certainty cash flow at a near-6% yield is exactly what he wants heading into an uncertain tape.
- The mainline is a moat. It’s going to be very tough for any new pipeline to beat the existing system.
- Unloved deals, now paying off. The utility acquisitions from a few years back — criticized at the time — now add real stability and balance.
- Opportunistic upside. He read the recent Blackstone asset deal as a bargain Enbridge could integrate well. “We’ll start on first base at 6% and work our way back from there.”
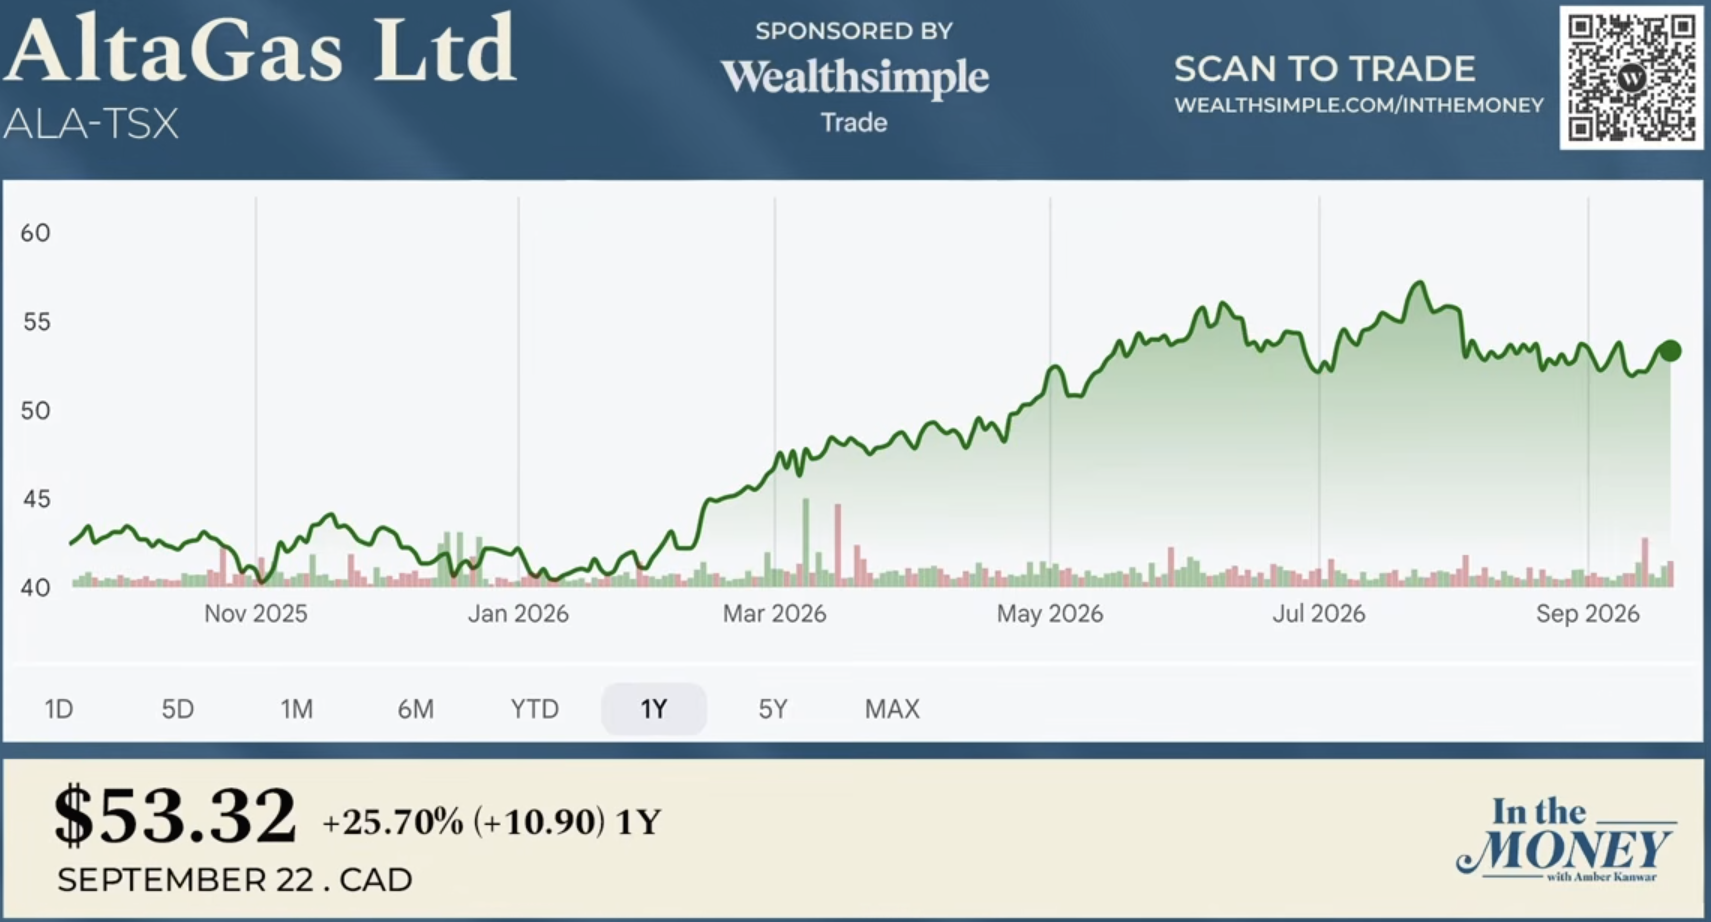
3. AltaGas (ALA) — the growthier one
Up ~30% on the year, ~2.5% yield — the one you buy for growth, not the dip.
- Directly linked to LNG. A smaller processing footprint than Pembina, but tied straight into LNG in northeast B.C.
- LPG export upside. Growing propane, butane and natural gas liquids export capacity it can vertically integrate — more processing and more export volumes.
- A growthier U.S. utility. Accelerated replacement work makes its utility arm growthier than most, adding stability to the story.
- The most dividend growth of the three. Lower yield because it’s already run, but he expects the strongest dividend growth here — and sees it holding up when markets hit a weak point.
DISCLAIMERS: This text AI generated and should be checked against actual delivery. The content provided in this podcast is for informational purposes only and does not constitute financial, investment, or professional advice. The views expressed by the host and guests are their own and do not necessarily reflect the opinions of any organization or company. The host and guests may maintain positions in any securities discussed on the podcast. Always consult with a qualified financial advisor or professional before making any investment decisions.