Canadian small caps have been left for dead. After two decades of disappointing performance, shrinking investor interest, and a steady exodus of institutional capital, is there any reason to believe a comeback is coming? Or has the market fundamentally changed for good? On this episode of In the Money with Amber Kanwar, Jeff Tory, Chair, Partner, Director, Portfolio Manager at Pembroke Management, makes the case that Canadian small caps could be approaching a major turning point.
Pro Picks is brought to you by ATB Financial. With over $100 billion in assets, ATB Financial is powering possibilities for more than 843,000 financial services clients. ATB Cormark Capital Markets is a leading North American investment firm providing holistic corporate and capital markets advice and full-service financial solutions. Visit www.ATB.com/inthemoney for more information.
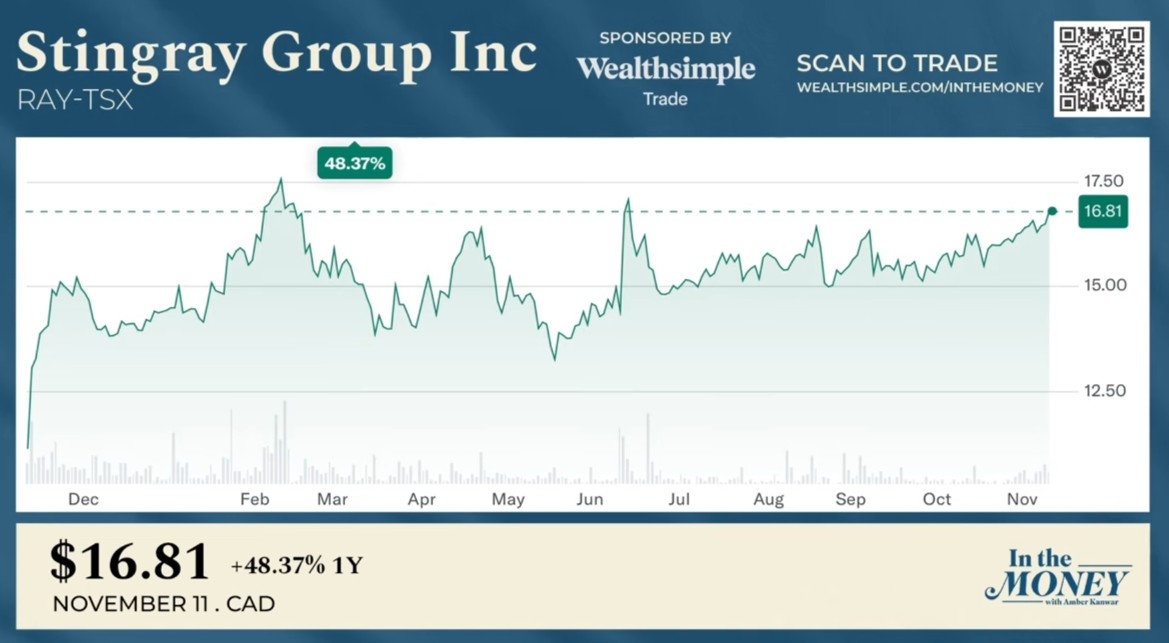
RAY.A — Stingray Group
A new-media business still valued like old media
- It’s more than the Yule log. Stingray started out distributing cable music channels. It now owns, curates and distributes music globally, selling mostly to other businesses. Partners include U.S. cable companies and Amazon, which shares revenue with Stingray for its music.
- Streaming TV is the growth engine. Stingray has won a lot of space on free, ad-supported channels on smart TVs, such as Samsung’s. Its viewership is growing quickly, and more viewers means more ad revenue. It’s using the same digital ad-selling approach across all its businesses, including radio.
- The TuneIn deal is the next catalyst. TuneIn was Stingray’s biggest acquisition ever. Jeff says 2027 will be the first full year to show the revenue and profit gains from combining the two businesses. The last quarter was “a little squishy,” and the stock has stalled since the deal.
- Insiders are betting on it. About 40% of the company is owned by insiders, including CEO Eric Boyko. Stingray took on debt both to buy TuneIn and to buy back its own stock. Jeff likes that, because insiders only buy when they expect to make money. Based on the free cash flow the company and its analysts expect, he says the stock is “way too cheap for the growth rate.”
AGF.B — AGF Management
A cash-rich asset manager the market has priced at three times cash flow
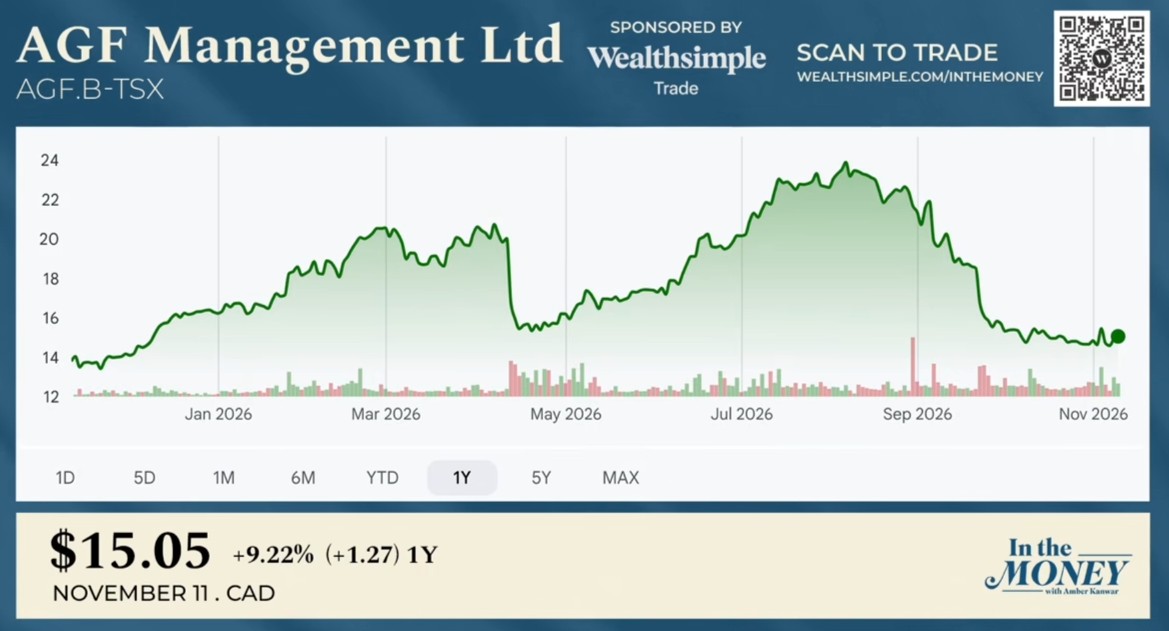
- The turnaround worked. Under CEO Judy Goldring and chair Blake Goldring, AGF improved fund sales, lifted fund performance into the top quartile, and built a private-assets business, AGF Capital Partners. The stock ran from cheap to about $24.
- Then it fell to about $15. The selloff began in August over confusion about how the private-assets business is accounted for. AGF owns a $430 million portfolio of private investments, including infrastructure. That portfolio is marked to market each quarter, and its performance fees are lumpy. Jeff says the market misread both.
- The $430 million becomes cash. The portfolio should be fully liquid within two years. It’s a large share of AGF’s market value, and the company has no debt. That money can go to buybacks, acquisitions or dividend increases.
- The valuation gap is huge. Jeff estimates AGF trades at about six times 2028 EBITDA, with a 15% free cash flow yield. Strip out the investment portfolio and the core business is valued at about three times EBITDA, while generating $140 million of free cash flow a year. By comparison, he says Guardian Capital, a similar business, was bought at about 11 times.
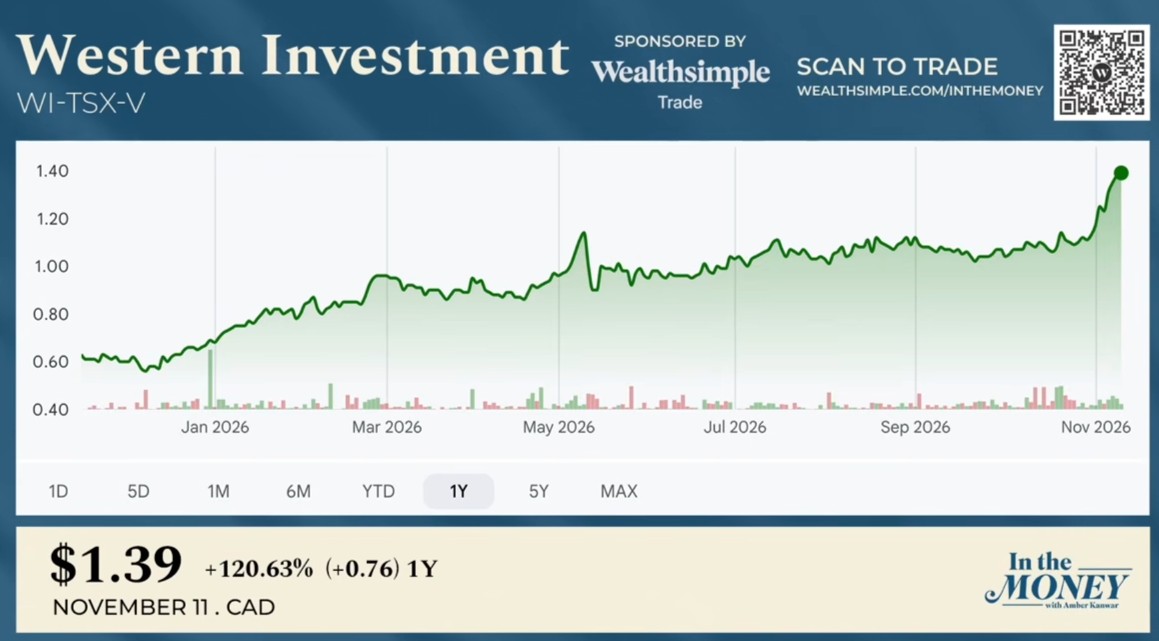
WI — Western Investment Company of Canada
A tiny insurer trying to build a mini Fairfax
- A rebuilt business. Western Investment started as a private-equity vehicle backing Western Canadian companies. In November 2024 it raised $30 million to take full ownership of Fortress Insurance. Since then it has wound down the private-equity holdings and moved that money back into insurance.
- Experienced backers. It’s backed by Scott Tannas, who built and sold Western Financial Group to Desjardins, and Paul Rivett, formerly of Fairfax and Torstar. Fortress is run by a young operator taking on Canada’s big, sleepy insurers. The plan follows Fairfax and Berkshire Hathaway: hire smart operators, keep them invested in the company, and let them run their businesses.
- It just did its first big deal. It bought a farm insurer that covers cattle in transit. Jeff calls it unglamorous but a great business, bought at a great price. Western used its $50 million in cash and raised another $50 million through Desjardins. Tannas has come back to run the company.
- It’s still small and overlooked. Shares are up 65% this year, but the market value is still under $200 million. Western has about $50 million to deploy and a list of possible acquisitions. Jeff’s view: “If you’re patient, you’re going to wake up and see compounding over the next five years.”
Don’t miss our next episode!!
DISCLAIMERS: This text AI generated and should be checked against actual delivery. The content provided in this podcast is for informational purposes only and does not constitute financial, investment, or professional advice. The views expressed by the host and guests are their own and do not necessarily reflect the opinions of any organization or company. The host and guests may maintain positions in any securities discussed on the podcast. Always consult with a qualified financial advisor or professional before making any investment decisions.