Canadian small caps have been left for dead. After two decades of disappointing performance, shrinking investor interest, and a steady exodus of institutional capital, is there any reason to believe a comeback is coming? Or has the market fundamentally changed for good? On this episode of In the Money with Amber Kanwar, Jeff Tory, Chair, Partner, Director, Portfolio Manager at Pembroke Management, makes the case that Canadian small caps could be approaching a major turning point.
Looking to invest in high-quality companies without high fees? The HAMILTON CHAMPIONS™ suite of ETFs offers exposure to diversified portfolios of equity champions across tech, financials, utilities, and dividend strategies, all with a low 0.19% management fee, designed to help you stay invested with confidence for the long term. For more information on the HAMILTON CHAMPIONS™ suite, visit: www.hamiltonetfs.com/hamilton-
Here are five things to know today
1.
Nvidia leadership crisis weighs on stocks
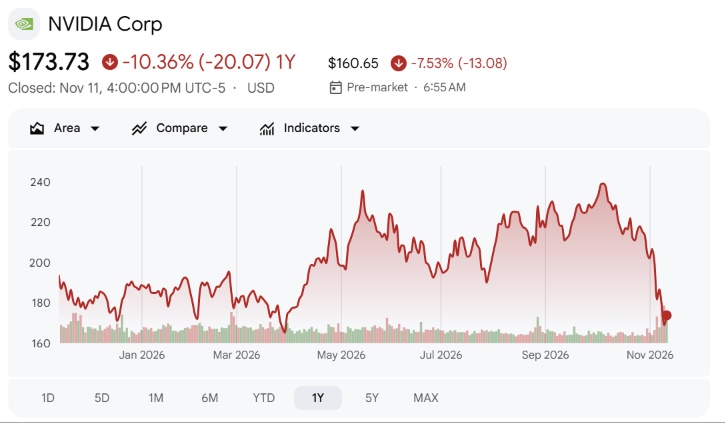
Nvidia is down 8% pre-market on reports CEO Jensen Huang had a second affair with a direct report, in addition to his affair with an alleged Chinese spy. The board is preparing to oust him. The discovery of a second affair appears to be the straw that broke the camel’s back with the downgrades rolling in this morning: Bernstein, William Blair and Evercore have all downgraded. The key question is who will take over? Tim Cook is being floated as a dark horse option. Perhaps a more realistic solution could come internally. Colette Kress, the current CFO, is seen as a viable option.
This won’t be an easy decision for the board, especially considering half have been there for more than 10 years and three of them have been there for 30 years. All of this has led to meaningful multiple compression, but don’t get lured in, argues Evercore’s Mark Lipacis in his downgrade. “While NVDA’s P/E compressed from 26x in May-26 to 12x today, we think the uncertainty around the CEO’s future at the company, lack of succession plan and our expectation for continued upwards revisions to forward EPS will translate to continued P/E compression,” he wrote. Sure, earnings may be going up but that is not the only issue for the AI trade. Nvidia became known as the “central bank of AI” backstopping some $500 billion worth of deals. The concern now is that whoever the new CEO is, he or she won’t have the same license to cut checks.
Nvidia’s downfall could be a windfall for rivals AMD and Broadcom which are both trading +1% in premarket. Money coming out of Nvidia will need a new home and increasingly, money has been rotating into healthcare and consumer staples which are the two best performing sectors over the past month. The rotation out of tech has been favouring the Dow, the TSX and the equal-weight S&P 500 which are all outperforming the S&P 500 since the beginning of October.
For what it’s worth, I’m not buying Nvidia here. Loyal readers may be surprised, given my habit of falling for broken stories on sale. But I always figured Nvidia would eventually peak, and I’m not smart enough to know when or how. Without its visionary CEO, I don’t see a clear path to avoiding the classic semiconductor cycle.

2.
Canadian Tire beats profit expectations
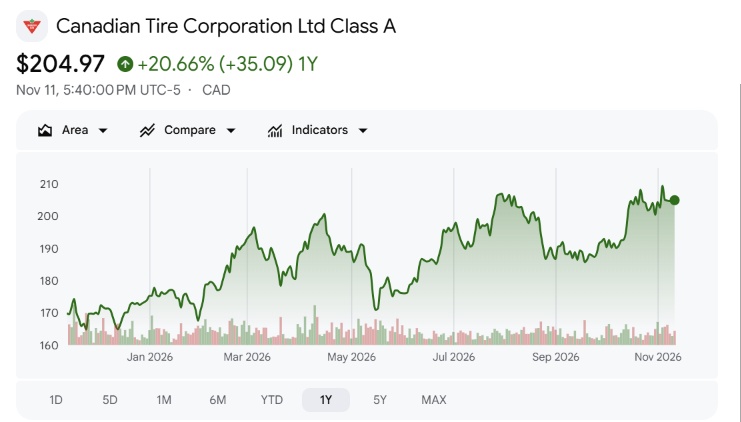
Same-store sales at Canadian Tire’s namesake brand, Sport Chek and Mark’s were all better than expected and above 3%. It also boosted its dividend for the 17th consecutive year and sports a yield of 3.5%. Online sales were a bright spot as well increasing nearly 25% in the quarter. The strength is reflected in the stock which is trading near a record high last seen in 2021. The big question is whether momentum can continue into the holiday season and we’ll look for colour on that during this morning’s conference call.
3.
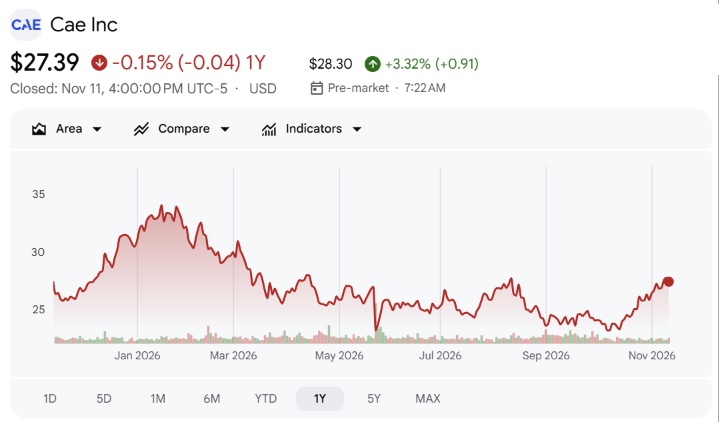
CAE +3% pre-market after earnings beat, lifted forecast
The world’s largest pilot trainer, which sells flight simulation software, beat profit expectations even as sales fell slightly. It also raised its profit forecast for fiscal 2027 to $1.28-$1.35/share which is higher than consensus sitting at $1.27/share. The company also increased its margin forecast suggesting that it is starting to reap the benefits of turnaround efforts of its civil and defense business lines. Under CEO Matthew Bromberg, the company has been focused on rationalizing its portfolio, having better capital discipline and improving operations. “Overall, a constructive update with CAE delivering against its transformation plan, driving stronger profitability, cash generation, increasing guidance, and accelerating buybacks,” wrote Stifel’s Daryl Young. I own Cae (see, can’t help myself when it comes to a turnaround!)
Cae on NYSE
4.
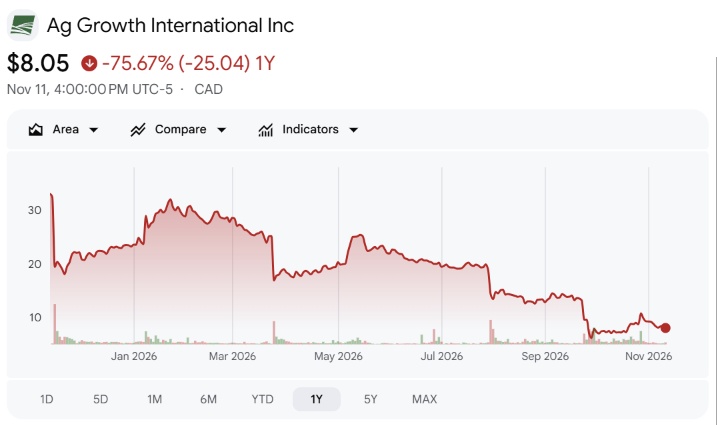
Profit at Ag Growth plunges
The story is still pretty ugly at the grain-handling company with profit falling 45% from last year, worse than feared. Sales declined in key markets including continued weakness in Brazil. However, there was an uptick in farm demand for portable equipment. Its debt levels are coming down, but because profitability is sinking the leverage ratio actually ticked up. The company is in the middle of a strategic review with CIBC and Bank of America as advisors. “We continue to view elevated leverage, Commercial margin pressures and refinancing requirements as key near-term overhangs,” wrote Steve Hansen at Raymond James.
5.
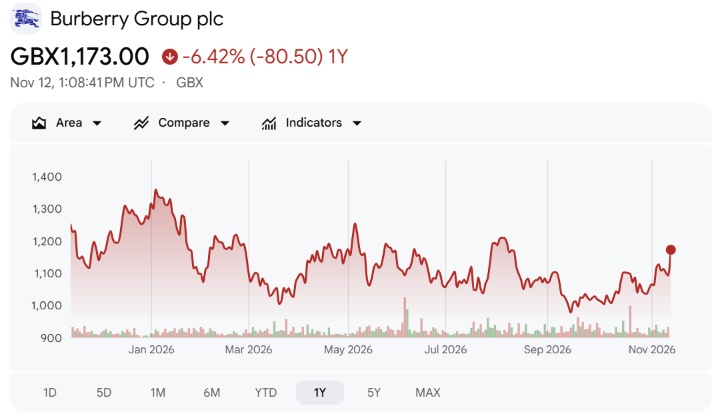
Burberry soars +8% on better sales and profit
Luxury has been dead money for over a year, but Burberry is bucking the trend thanks to sales of its iconic trench coats. Burberry has been reducing price points in an effort to reach aspirational shoppers and those efforts appear to be paying off this quarter. Chinese sales were a bright spot, increasing 5%, faring better than rivals in that market. Two years in, the turnaround is bearing fruit, with every segment posting sales growth.
Don’t miss the next episode!